Partner – Employment Solutions
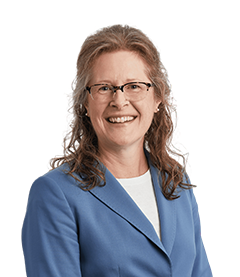
Elizabeth is a committed tax professional, who delights in helping her clients design their employment tax systems and policies and meet their obligations in the most efficient and effective manner. She has extensive experience in providing fringe benefits tax and salary packaging advice to not-for-profit bodies, corporate clients and government organisations. She specialises in the various areas of employment taxes and also has experience in GST.
Elizabeth provides advice to employers in many industries, including government, manufacturing, mining, retail, finance, leasing, education, not-for-profits and others. This encompasses identifying risk areas, advising on ensuring compliance with legislative requirements, planning to minimise FBT, assessing FBT systems, preparing policy manuals, assisting with implementing new policies and providing training to staff.
Over the years, Elizabeth has served on several professional body committees and has been invited to participate in a number of ATO and government consultations. She is also a speaker at various professional body events and is a past Board Director of Grant Thornton Australia.
Experience
In particular, Elizabeth’s areas of expertise are as follows:
- Salary packaging policies and implementation
- Fringe benefits tax technical issues, systems and compliance procedures
- Superannuation guarantee, including remediation
- Singe Touch Payroll
- Remuneration structuring
Qualifications
- Bachelor of Economics, Monash University
- Fellow of Chartered Accountants Australia and New Zealand
- Fellow of the Tax Institute
- Member of the Australian Society of Certified Practicing Accountants
- Graduate of the Australian Institute of Company Directors
- Member and past Chair of the Taxation Institute of Australia FBT Subcommittee
- Past member of the ATO's National Tax Liaison Group FBT Subcommittee
- Past member of Federal Treasury’s Not for Profit Sector Tax Concession Working Group
- Member of the ATO's FBT Stakeholder Group