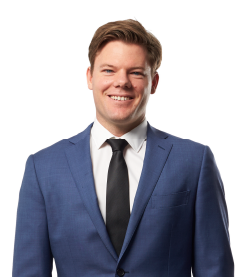
Partner & Head of Tax – Perth
Mark leads the tax team in Grant Thornton's Perth office. He is an experienced corporate tax practitioner with over 20 years of experience providing Australian taxation assistance for listed companies, large private entities and multinational groups. He specialises in the provision of tax advisory, tax compliance and tax due diligence work. Mark has particular focus and experience in Mining and Resources, Professional Services (particularly engineering and mining support services) and Technology industry sectors.
Prior to joining Grant Thornton, Mark worked for a Big 4 accounting firm in its Perth and Sydney offices.
Examples of Mark's work:
- Provision of tax advice to private companies planning to list on the ASX
- Tax Governance Framework assistance
- Successful dispute resolution with the ATO in respect to international tax matters
- International and domestic tax structure planning
- Tax loss testing
- Tax consolidation work, including allocable costs amount and available fraction work
- Tax due diligence work from both the sell and buy side
Qualifications
- Graduate Diploma of Applied Finance, Kaplan (Post graduate degree)
- Chartered Accountant – Affiliate Membership