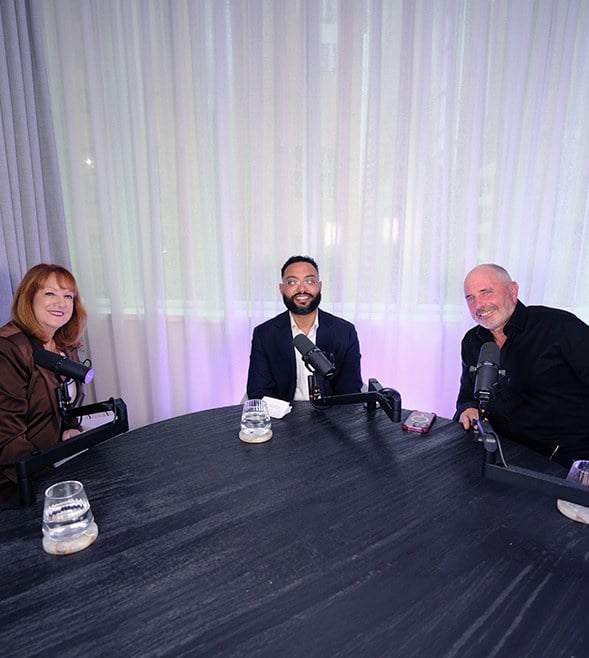
In this special episode of Beyond the Numbers with Grant Thornton, Private Enterprise Partner Beau Chaperon hosts the show and sits down with Lea Hicks and Richard Fox to discuss resilience, leadership and the relationships that help individuals and organisations navigate change and achieve lasting success for Western Sydney.
Filter insights by:
Showing 12 of 38 content results
New “EET election” option for discretionary trusts to avoid the minimum 30 per cent without having to restructure, but creates inflexibility.
For many successful families, creating wealth is only the beginning. As your businesses, investments and family interests grow, arrangements that once worked well can become difficult to manage.
In estate planning, the focus is often on technical elements like drafting a will, appointing executors, minimising tax, and ensuring assets pass as intended. While these steps are important, they only form part of the picture.
The 2025 Grant Thornton Family Business Report revealed that only 19 per cent of family businesses have a documented succession plan in place. This finding is both striking and concerning, especially at a time when generational transition has never been more complex, and the stakes have never been higher.
As family businesses transition from one generation to the next, more family members become involved in the business. What usually begins with a couple of founding members quickly grows to include siblings, and cousins each with their own experiences, personalities and perspectives.
Our 2025 Family Business Survey revealed a recurring theme that presents both a challenge and an opportunity: succession planning. Succession is often viewed as a pivotal moment in a family business’s lifecycle.
For family businesses, this demographic milestone signifies an important moment. As many founders and senior leaders approach retirement age, the need for thoughtful succession planning and effective intergenerational collaboration has never been greater. Navigating this transition isn’t just about handing over the reins – it’s about evolving the business while preserving its legacy.
Managing family businesses can be complex as it involves navigating daily operations as well as family dynamics. Because of this, it’s important both your succession and estate plans align. While documenting your succession plan is key, it’s equally important your estate plan legally reinforces your vision for the future.
Ideally, you want 5-10 years to plan for retirement. The longer you allow yourself, the easier it will be to reach your goal. If selling the business part of your plan, the aim is to secure the best price and maximise your return after tax. So, what factors should you consider for retirement?
Integrating innovation and legacy is crucial for the continued success of family businesses. Legacy provides a sense of identity, purpose and continuity, while innovation drives growth and competitiveness. So how can you balance the two?
As family businesses evolve, financial transparency has become a vital element for fostering growth and trust. As the baton passes to the Rising Generation, a new wave of openness and accountability is reshaping the way family business discuss money.