Family Trust Distributions Tax: avoiding the pitfalls
InsightFamily trusts can benefit from tax concessions that come with making a Family Trust Election (FTE) but risk Family Trust Distribution Tax (FTDT) if not managed well.
Remarkable Journeys with Jess Fox: Conversations with our clients, people and community. Listen now.

Most private entities reporting in compliance with the Corporations Act 2001 can benefit from relief granted by ASIC – allowing lodgement of audited financial statements by 30 November, rather than 31 October. This allows the benefit of hindsight for many entities, taking advantage of some of the lessons from the experience of others.
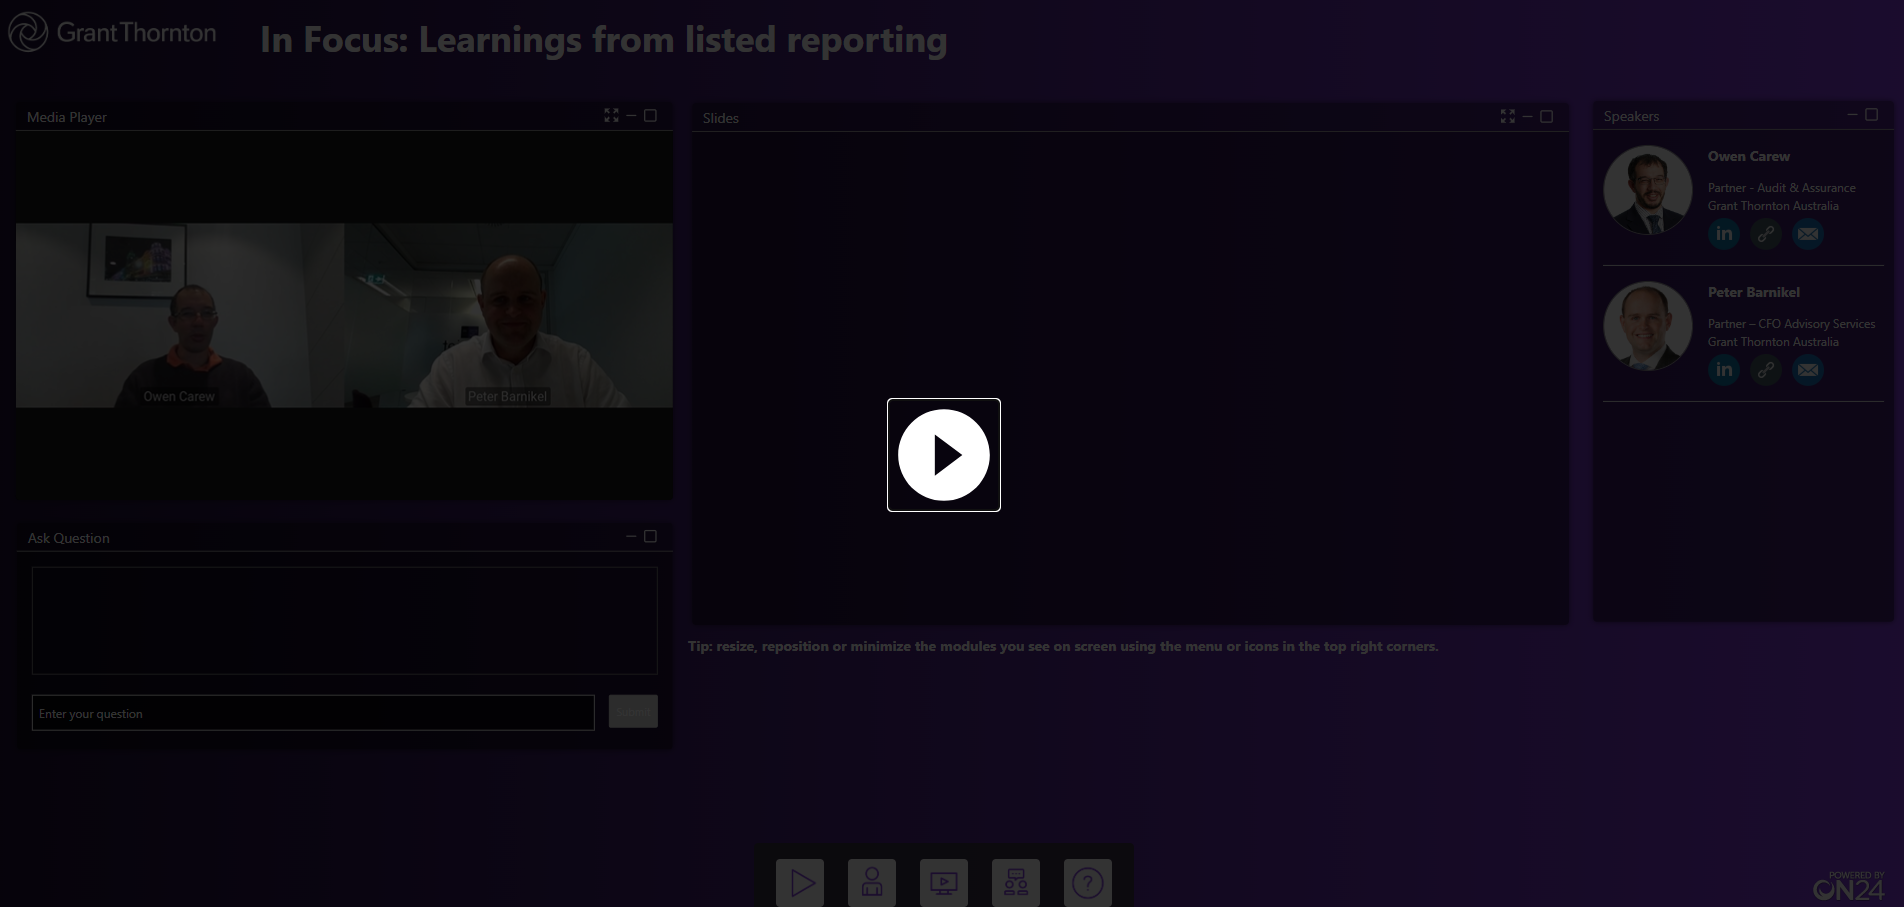
What can private reporters learn from work completed by listed entities to streamline their approach to reporting and audits, particularly while preparing general purpose financial statements for the first time?
Watch on demand as we discuss areas of accounting complexity you might encounter, particularly where our clients have required additional assistance. We’ll also explore first-time adoption of AASB 1060 General Purpose Financial Statements when moving from a special purpose reporting regime.
Partner
Family trusts can benefit from tax concessions that come with making a Family Trust Election (FTE) but risk Family Trust Distribution Tax (FTDT) if not managed well.
Like many countries, Australia taxes its residents on the income and capital gains they generate irrespective of where they are sourced. For ‘temporary residents’, understanding how the rules operate in detail – and even your relationship status – is necessary to determine your tax position.
New entities are often established as part of implementing property settlements. However, this could overlook one current focus area of the ATO – whether or not Family Trust Distribution Tax (FTDT) is payable due to distributions having been made by Family Trusts outside their ‘family group’.