Director – Tax
Corporate Tax
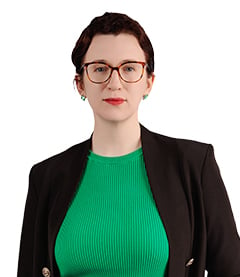
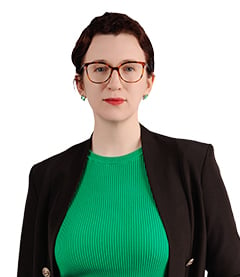
Jess is an experienced corporate tax adviser, having worked in both Australia and the UK. She manages a broad client portfolio, ranging from domestic start-ups to large international groups. Her clients span a range of industries, with a particular focus on real estate & construction and energy & resources. As leader of Perth's Real Estate and Construction industry team, Jess works closely with businesses across the sector and brings a deep understanding of the opportunities and challenges affecting the industry.
Jess prides herself on providing excellent client service and offering proactive and pragmatic advice.
Experience
- Merger & Acquisition transactions, advising both buy-side and sell-side parties on relevant tax issues.
- Tax governance
- Loss recoupment
- Tax consolidation
- Cross-border transactions
- Restructurings, including rollover relief.
Qualifications
- Bachelor of Commerce (University of Western Australia)
- Bachelor of Laws (University of Western Australia)
- Member of Chartered Accountants Australia and New Zealand (CAANZ)