Explore retail market insights, M&A trends, value drivers and growth opportunities shaping the sector, and learn how to build a stronger retail business.
Filter insights by:
Popular topics
Featured insights
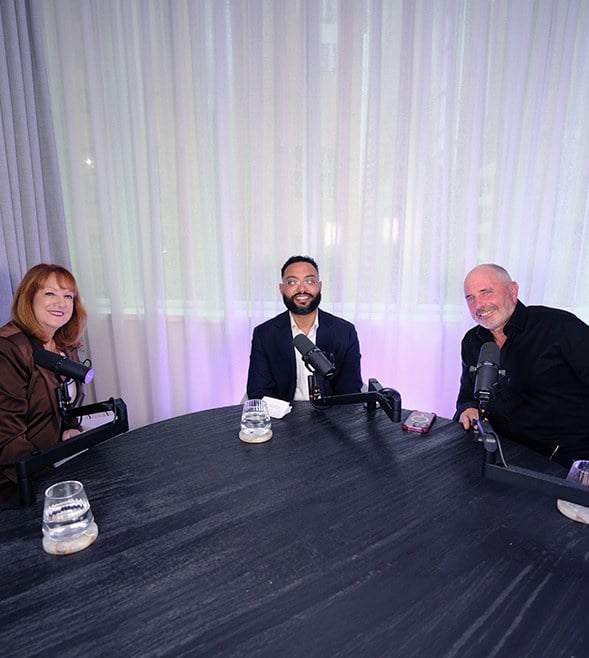
In this special episode of Beyond the Numbers with Grant Thornton, Private Enterprise Partner Beau Chaperon hosts the show and sits down with Lea Hicks and Richard Fox to discuss resilience, leadership and the relationships that help individuals and organisations navigate change and achieve lasting success for Western Sydney.
Legacy is often associated with the athletes, infrastructure and moments that capture public attention. Yet the foundations of a lasting legacy are built well before the event begins and continue long after it ends.
Latest insights
New entities are often established as part of implementing property settlements. However, this could overlook one current focus area of the ATO – whether or not Family Trust Distribution Tax (FTDT) is payable due to distributions having been made by Family Trusts outside their ‘family group’.
The Australian Tax Office (‘ATO’) on 11 June 2025 updated its Practical Compliance Guide PCG 2018/9 on corporate tax residence to reflect key changes including aligning tax compliance residence disclosures to the Consolidated Entity Disclosure Statement (‘CEDS’) for financial reporting purposes.
Section 99B of Australia’s tax law can trigger unexpected tax liabilities for residents receiving foreign trust distributions, including gifts, loans, and use of trust property. With increased ATO scrutiny and recent guidance, it’s vital to assess residency status, maintain clear documentation, and understand the tax implications before receiving overseas transfers.
Receiving money from overseas can trigger unexpected Australian tax consequences, especially when foreign trusts are involved. With the ATO increasing scrutiny on international transfers, including gifts, inheritances, and loans, it’s vital for Australian residents to understand their tax obligations. Section 99B of the Income Tax Assessment Act 1936 and recent ATO guidance highlight the risks of poor documentation and lack of planning. This article explores common scenarios, the importance of maintaining records, and how proactive tax planning can help avoid significant liabilities for both recipients and their overseas families.
The ATO has confirmed a stricter application of section 99B - taxation of foreign trust distributions, meaning more distributions or benefits from foreign trusts to Australian residents may now be taxable.
Australian Capital Territory Treasurer Chris Steel delivered his first budget on Thursday 24 June alongside Chief Minister Andrew Barr.
The New South Wales (NSW) State Government led by Labor Premier Chris Minns handed down the state’s budget on Tuesday 24 June 2025.
While the Division 296 tax is still yet to be legislated, it’s looking likely the tax will be introduced. For individuals who may be impacted by the change, it’s critical to understand how different scenarios might play out and what they should consider.
On Tuesday 24 June 2025, Queensland Treasurer David Janetzki handed down the Queensland State Budget – the first LNP budget in the state since 2014, following the Crisafulli Government’s win in the 2024 election.
In this Pride Month episode of The Remarkables, we sit down with Ben Bjarnesen – a police officer, educator and campaigner – to understand his journey and community impact.
As Australia moves away from legacy business payment systems like batch payments and cheques, the shift to real-time, account-to-account payments is transforming the way businesses interact – not just with their banks, but with each other.
The ATO’s draft guideline PCG 2025/D2 outlines how taxpayers must determine an arm’s length debt amount for related-party loans under transfer pricing rules. It challenges the use of guarantees to inflate borrowing capacity and introduces a risk assessment framework to classify arrangements by compliance risk. Robust documentation is essential to support deductions.