Outlining key tax considerations for a taxpayer once their aggregated group turnover is A$1 billion or more.
Filter insights by:
Popular topics
Featured insights
In this episode of Beyond the Numbers with Grant Thornton, AML/CTF expert Neil Jeans explores why organisations should assess their exposure, even if they think risk is low, and where businesses can start so they’re in the best defensive position should any issues arise.
R&D Tax Incentive reforms, RDTI reforms, R&D tax offset, innovation incentives, refundable R&D offset, non-refundable R&D offset, supporting R&D activities, Treasury consultation, research and development tax incentive, Federal Budget 2026-27, R&D tax changes, Australia R&D incentives, Innovation Incentives, R&D claims
Latest insights
The ATO has recently released guidance to assist in determining the application of the FBT exemption for EVs. There is some helpful clarification provided, but a few other areas remain ambiguous. Here are some of the highlights.
The ATO has amended PCG 2018/9 to extend the corporate tax residency transitional period until 30 June 2023 to allow taxpayers to change their governance arrangements with respect to central management and control of foreign incorporated subsidiaries. The ATO has stated that the transitional period will not be extended again.
We’ve made it to the other side of COVID-19, but what does this mean for businesses feeling significant headwind on the horizon post-pandemic?
On 16 March 2023 the Federal Government released its Exposure Draft (ED) legislation, which was first announced as part of its October 2022 Federal Budget Thin Capitalisation measures.
The Security of Critical Infrastructure Risk Management Program Rules (CIRMP) commenced on 17 February 2023 and was signed off by The Minister for Home Affairs the Hon Clare O’Neil MP (the Minister). This marks the beginning of the six-month transition period for responsible entities to adopt a written CIRMP.
This article is the second in a series where we discuss the stages of a payroll remediation project.
Quantification of losses in insurance claims often rely upon assumptions instructed or adopted by an expert.
Are you up to date on your TPAR obligations? The Australian Taxation Office has begun to actively issue failure to lodge penalties for businesses who are behind on their TPAR lodgements.
We’re currently experiencing a veritable shopping list of headwinds – inflation, interest rates, labour costs, fuel prices, and supply chain challenges – applying pressure on businesses across all industries. The need to balance cost control with sustainable growth is a fine needle to thread, and not all businesses and costs are created equal. With so many cost control levers to pull, as a CFO, where do you begin?
AASB 2020-3 amends AASB 116 to prohibit entities from deducting from the cost of an item of Property, Plant and Equipment, any proceeds from selling items produced while bringing property, plant and equipment to the location and condition necessary for it to be capable of operating in a manner intended by management. Instead, these proceeds and related costs are required to be recognised in profit or loss.
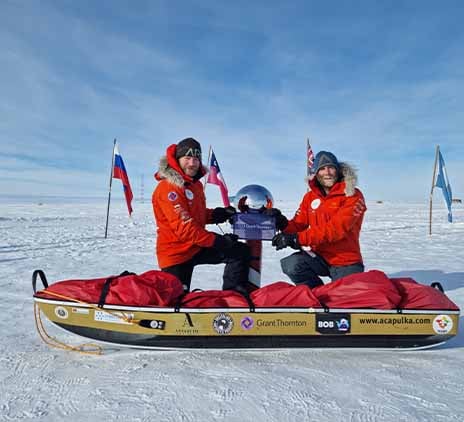
In this episode, Gareth and Richard talk about their journey across Antarctica, how they dealt with challenges using limited resources, and the little luxuries they enjoyed once they arrived home.
The Queensland Government announced that the expansion of Project Trust and Retention Trust Accounts originally scheduled to take effect 1 April 2023 will be extended by three years to 2025. Eligible contracts valued between $3m and $10m will now need to comply from 1 March 2025, and contracts above $1m will need to comply from 1 October 2025.